Why Understanding E&O Insurance Costs Matters for Your Business
The cost of e&o insurance typically ranges from $19 to $95 per month for most small businesses, with the national average around $60-$66 per month. However, your actual premium depends on several factors including your profession, business size, location, and coverage limits.
Quick Answer: What You'll Pay for E&O Insurance
- Low-risk businesses: Starting at $19/month
- Most small businesses: $50-$95/month
- National average: $60-$66/month
- Annual range: $250-$735/year
- Common coverage: $1 million per occurrence / $1 million aggregate
Errors and Omissions insurance—also called professional liability insurance—protects businesses and professionals from costly lawsuits when clients claim your services caused them financial harm. Even if you didn't actually make a mistake, defending yourself in court can cost tens of thousands of dollars.
For professionals across Long Island, from Patchogue to Medford, understanding these costs is critical. Whether you're a real estate agent in Holtsville, a consultant in Holbrook, or an accountant serving clients throughout New York, a single lawsuit could drain your savings and damage your reputation.
The real estate industry learned this lesson the hard way. As one source notes, "Many small businesses learn the hard way that lawsuits are more common than they assume." A missed deadline, a miscommunication with a client, or an oversight in your professional advice can all trigger expensive legal battles—even when you've done nothing wrong.
This guide breaks down everything that affects your E&O insurance costs in New York. You'll learn which factors push premiums up or down, how your specific profession impacts pricing, and practical strategies to reduce your insurance bill while maintaining strong protection. Whether you're shopping for coverage for the first time or looking to lower your current premium in Patchogue, Holbrook, Holtsville, or Medford, you'll find clear answers backed by real data.
Understanding the Average Cost of E&O Insurance
Let's talk numbers. When business owners first look into the cost of e&o insurance, they often want a simple answer: "Just tell me what I'll pay!" If only it were that straightforward.
The truth is, E&O insurance doesn't come with a one-size-fits-all price tag. Think of it more like buying a car—the sticker price depends on what you're driving, where you're driving it, and your history behind the wheel. That said, national averages give us a helpful starting point to understand what's typical.
What Most Businesses Actually Pay
Across the country, small businesses typically pay somewhere between $50 and $95 per month for E&O coverage. The national average hovers around $66 per month, though the median cost (the middle point where half pay more and half pay less) comes in at about $42 monthly.
Some lucky low-risk businesses start as low as $19 per month. On an annual basis, many small business owners spend between $250 and $500 per year for their policy, though this range can stretch considerably depending on your specific situation.
For context, real estate professionals across the country see average yearly costs around $665—that's roughly $55 per month. Insurance agents, who you'd think would know how to get a good deal, pay an average of about $65 monthly.
Why New York Businesses See Different Numbers
Here's where it gets interesting for those of us on Long Island. These national figures are useful benchmarks, but they don't tell the whole story for businesses operating in New York. Our state has its own regulatory environment, legal landscape, and market conditions that all influence pricing.
A consulting business in Holbrook might see rates that look quite different from a similar business in, say, Austin or Atlanta. The same goes for professionals in Patchogue, Holtsville, and Medford—local factors matter more than you might think.
New York's legal environment tends to be more active than many other states, which insurers factor into their pricing. The cost of doing business here, the regulatory requirements, and even the economic profile of Long Island communities all play a role in shaping what you'll actually pay for coverage.
Setting Realistic Expectations
Understanding these averages helps you know what's reasonable when you start getting quotes. If someone quotes you $200 per month for basic coverage when you run a low-risk bookkeeping business, you'll know something's off. Conversely, if you're an architect in Medford getting quotes around $100 monthly, you'll recognize that's in the expected range for your profession.
But averages only tell part of your story. Your actual cost of e&o insurance depends on a whole mix of factors specific to your business—your industry, your revenue, your claims history, and the coverage limits you choose. We'll dig into all of these factors next, so you'll understand exactly what drives your premium up or down.
Want more detailed insights into current pricing trends? Check out this resource: Average Cost of Errors and Omissions Insurance 2025 – LatestCost – Real-Time Price Insights.
Key Factors That Determine Your E&O Insurance Premium
When you ask us at Bay Harbour Insurance Agency how much your E&O insurance will cost, we can't give you a number off the top of our heads—and anyone who does is probably guessing. The cost of e&o insurance comes down to a detailed underwriting process where insurers look at your business from every angle. They're essentially asking: "How likely is this business to face a lawsuit, and how expensive might that lawsuit be?"
Think of it as a risk assessment custom specifically to your professional services. The way you do business in Patchogue isn't identical to how someone operates in Texas, and insurers know that. Every factor they examine—from what you do to where you do it—connects with the others to create your unique risk profile. A consultant in Holbrook faces different risks than an architect in Medford, and your premium reflects that reality.
How Industry and Profession Impact the cost of e&o insurance in Long Island
Your profession is the biggest driver of your E&O insurance costs, hands down. Some industries simply carry more risk than others, and insurers price accordingly.
High-risk professions include lawyers, accountants, architects, and financial advisors—basically anyone whose mistake could cost a client serious money. Real estate agents on Long Island fall into this category too. When you're handling six-figure or seven-figure property transactions, the potential for a costly error is real. One missed disclosure or miscommunication about a property boundary can trigger a lawsuit that drags on for years. The average yearly cost for E&O insurance for real estate professionals is about $665, which works out to roughly $55 per month.
On the flip side, lower-risk professions like notaries and bookkeepers typically enjoy much more affordable rates. The potential financial impact of their mistakes is generally smaller, so insurers charge less to cover them. Insurance agents themselves pay an average of $65 per month (about $781 annually) for their E&O coverage. For Life & Health Agents licensed less than two years, some programs start as low as $26.25 per month.
The specific services you offer in Holtsville or anywhere across New York will determine where you land on this risk spectrum. If you're wondering whether your profession is considered high-risk, just ask yourself: "If I make a mistake, could it cost my client thousands or even millions?" If the answer is yes, expect higher premiums.
Business Size, Revenue, and Location's Role
Size matters when it comes to E&O insurance. The more employees you have and the higher your annual revenue, the more exposure you have to potential claims. It's simple math: more employees mean more client interactions, more projects, and more opportunities for something to go wrong. A larger business also typically handles bigger contracts, which means bigger potential losses if a claim arises.
A solo consultant working from home in Holbrook will pay considerably less than a firm in Patchogue with fifteen employees and multi-million-dollar contracts. That's not because the solo consultant is necessarily better at their job—it's just that their potential for a catastrophic claim is lower.
Location plays a surprisingly big role in your premium too. Insurance rates vary significantly across different states and even within regions of New York. This happens for several reasons: state regulations differ, some areas are more litigious than others, and the cost of doing business varies by location. If you're in an area known for frequent lawsuits or high jury awards, insurers will factor that into your rate.
For businesses across Long Island, the legal environment in New York is definitely considered in your premium calculations. A professional in Medford, NY might see different rates than someone doing identical work upstate, where the cost of living and potential damages in lawsuits could differ. State regulations in New York also influence how policies are structured and priced, which is why comparing your quote to a national average only tells part of the story.
The Relationship Between Coverage Limits, Deductibles, and the cost of e&o insurance
Two numbers on your E&O policy will have a direct impact on your premium: your coverage limits and your deductible. Understanding how these work helps you make smarter choices about your coverage.
Coverage limits are straightforward—they're the maximum amount your insurer will pay for claims. You'll see two numbers on most policies: a per-occurrence limit (the max for any single claim) and an aggregate limit (the max for all claims combined during your policy period, usually one year).
Most small business owners—about 63%—choose a policy with $1 million per occurrence and $1 million aggregate. This is often called a "one million, one million" policy. It's become something of an industry standard because it provides solid protection without breaking the bank. But here's the key: higher limits mean better protection, but they also mean a higher premium. If you opt for $2 million in coverage, expect to pay more each month. For businesses in Holbrook and across Long Island, we help you figure out what limits make sense based on your actual exposure. You can learn more about securing the right professional liability coverage here: Secure Business Professional Liability.
Your deductible is the amount you'll pay out of your own pocket before insurance kicks in. Typical deductibles range from $500 to $2,500, with many businesses choosing a $2,500 deductible. Here's the trade-off: the higher your deductible, the lower your monthly premium. You're essentially telling the insurer, "I'll handle the small stuff, you cover the big disasters." This reduces their risk, so they charge you less.
But don't just pick the highest deductible to save money. Make sure you can actually afford to pay that amount if a claim comes in. There's no point in saving $30 a month if you can't come up with $5,000 when you need it. For your business in Patchogue or Holtsville, it's about finding the balance between manageable monthly costs and protection you can actually use.
How Experience and Claims History Affect Your Rates
Your track record matters—a lot. Insurers look at both how long you've been in business and what's happened during those years.
Years in business gives insurers confidence (or concern). If you're brand new, you're something of an unknown quantity. You haven't established solid client relationships, refined your processes, or proven you can handle the challenges that come with your profession. That uncertainty often translates to higher premiums. It's not personal—it's just that insurers have seen too many new businesses stumble in their first few years.
Established businesses on Long Island with a solid track record are viewed as safer bets. If you've been successfully serving clients in Medford or Holtsville for a decade without major issues, insurers see you as lower risk. That stability usually translates to more favorable rates.
Claims history is even more important. If you've filed E&O claims in the past, insurers will definitely take notice. Past claims suggest you might file future claims, which makes you a higher risk. This can result in increased premiums, surcharges added to your policy, or even difficulty finding coverage from certain providers.
A clean record is your best friend when shopping for E&O insurance. If you've been practicing in Patchogue without any claims, that speaks volumes about your professionalism and risk management. Insurers reward that with better rates.
One more thing: maintaining continuous coverage matters. Gaps in your E&O insurance can raise red flags and potentially create issues with "prior acts" coverage—which protects you for work you did before your current policy started. If you let your coverage lapse, you might not be protected for work completed during that gap, even if a claim comes in later. Keeping continuous coverage shows insurers you take your professional liability seriously.
Smart Strategies for Lowering Your E&O Insurance Bill
Now that you understand what drives the cost of e&o insurance, let's talk about what you can actually do to bring those numbers down. For business owners across Long Island—whether you're running a consulting practice in Patchogue or managing a real estate office in Holbrook—these actionable strategies can lead to real savings while keeping your business protected.
The good news? You have more control over your E&O insurance costs than you might think.
Proactive Risk Management
The most effective way to lower your cost of e&o insurance is surprisingly straightforward: reduce the chances of a claim happening in the first place. Insurance companies reward businesses that demonstrate they're serious about managing risk. When you show insurers you've built a solid foundation of professional practices, they respond with better rates.
Think of it this way—every detailed client contract you create is money in the bank. When you clearly spell out the scope of work, deliverables, timelines, and expectations in writing, you're eliminating the ambiguity that leads to disputes. For your Patchogue or Holbrook business, this documentation becomes your first line of defense.
Quality assurance protocols matter more than you'd think. Simple checklists and review processes catch errors before they reach clients. When you implement these systems, you're not just protecting your reputation—you're actively demonstrating lower risk to your insurance provider.
Employee training programs are another powerful tool. A well-trained team makes fewer mistakes, and insurers recognize this. Regular education sessions show you're committed to professional excellence, which translates directly to your risk profile.
Clear communication with clients throughout every project prevents misunderstandings from snowballing into claims. When challenges arise, addressing them promptly and transparently keeps small issues from becoming big problems. This is especially important in the business environment of Medford and throughout New York.
Documentation is your best friend. Keep detailed records of every client interaction, decision, piece of advice, and project milestone. If a claim ever arises, comprehensive documentation can be the difference between a quick resolution and a lengthy dispute. Following professional best practices and industry standards isn't just good ethics—it's proof of your due diligence.
When you prioritize these risk management strategies in your Holtsville or Patchogue operations, you're building a track record that insurers value. A clean claims history opens doors to better rates and more favorable policy terms.
Structuring Your Policy for Savings
Beyond preventing claims, how you set up your E&O policy directly impacts what you pay. At Bay Harbour Insurance Agency, we help businesses across Long Island structure their coverage to maximize both protection and affordability.
Your deductible choice can significantly affect your premium. Opting for a higher deductible means accepting more initial risk if a claim occurs, but it typically reduces your annual premium costs by 10% to 20%. The key is choosing a deductible your Medford or Holtsville business can comfortably handle without creating financial strain.
Payment timing matters more than most business owners realize. Paying your premium annually instead of monthly often open ups a discount. While it requires a larger upfront payment, the long-term savings add up. It's one of those simple changes that rewards planning ahead.
Bundling your E&O coverage with other policies creates opportunities for multi-policy discounts. If you need General Liability Insurance NY or other business coverage, combining them with your E&O policy can reduce your overall insurance costs while giving you comprehensive protection.
Shopping around isn't just smart—it's essential. Different insurers evaluate risk differently, which means premiums can vary significantly for the same coverage. We encourage our clients throughout Holbrook and across Long Island to compare options. Ensuring you have the right coverage for your Medford or Holtsville operations means finding the policy that fits both your risk profile and your budget.
Maintaining continuous coverage is crucial for E&O insurance, which operates on a "claims-made" basis. Gaps in your policy can complicate coverage for past work and may result in higher premiums when you restart coverage. Consistent protection demonstrates stability and keeps your rates favorable.
By thoughtfully managing risk and strategically structuring your policy, you can take real control over your cost of e&o insurance. These aren't just theoretical tips—they're practical strategies that work for businesses right here in Patchogue, protecting your professional reputation and your financial future.
Frequently Asked Questions about E&O Insurance
After years of serving professionals across Long Island, we've noticed that certain questions about E&O insurance come up repeatedly. Whether you're a real estate agent in Patchogue, a consultant in Holbrook, or a freelancer in Holtsville, these are the answers that will help you make informed decisions about protecting your business.
Is E&O the Same as Professional Liability Insurance?
Here's the simple answer: yes, they're the same thing. Errors and Omissions insurance and Professional Liability insurance are just two different names for identical coverage. It's like how some people say "soda" while others say "pop"—different words, same product.
The terminology you hear often depends on your industry. Healthcare professionals typically call it "malpractice insurance," while technology consultants and business advisors usually refer to it as "E&O." Regardless of what it's called, the core function never changes: protecting you from financial losses when clients claim your professional services caused them harm. For professionals throughout New York, understanding that these terms are interchangeable helps cut through the confusion when shopping for coverage.
What Does an E&O Policy Actually Cover?
Think of your E&O policy as a financial shield against the unexpected costs of doing business. When a client believes your professional services fell short, the expenses can pile up fast—even when you did nothing wrong.
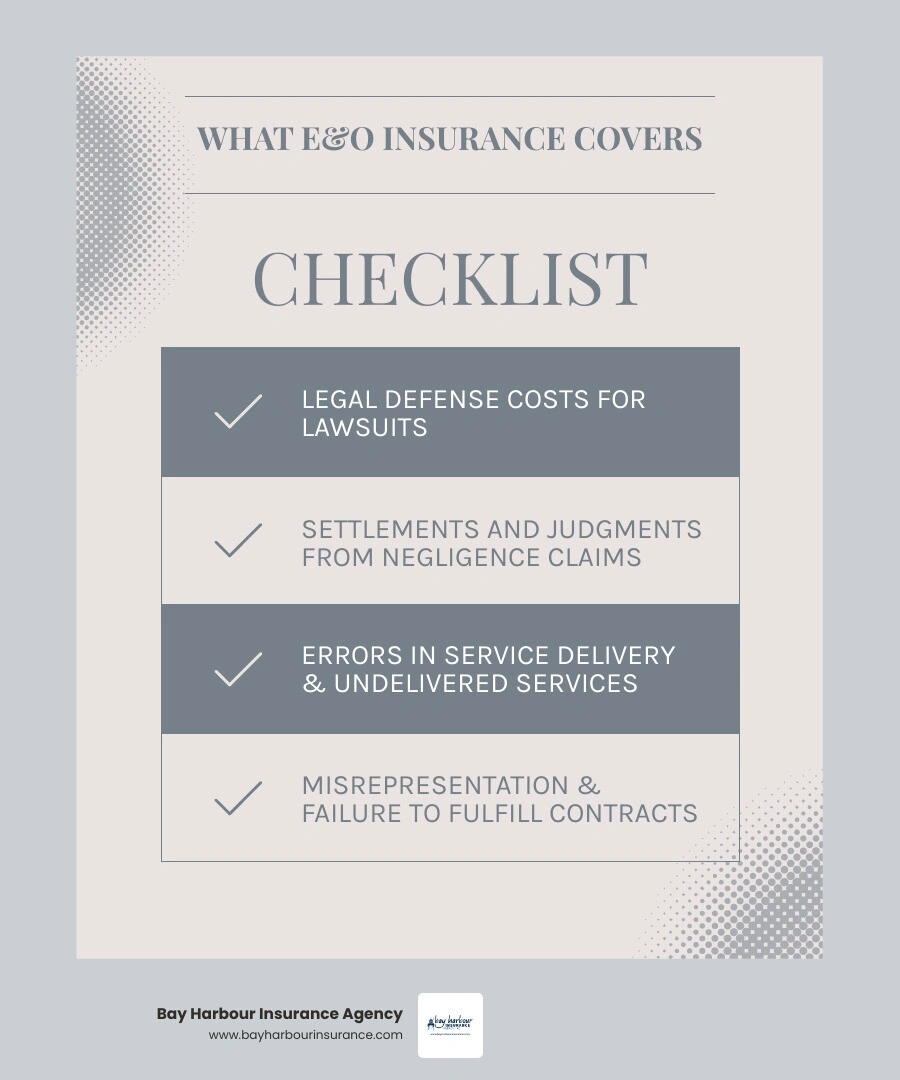
Your policy steps in to cover legal defense costs, which can be substantial. Attorney fees, court costs, expert witnesses, and other litigation expenses are all included, and these costs alone can reach tens of thousands of dollars. Beyond defense, your policy also covers judgments and settlements if you're found liable or if you reach an agreement with a client, up to your coverage limits.
The types of claims covered include allegations of negligence or mistakes in your work, undelivered services when a client says you didn't fulfill your contractual obligations, and misrepresentation where someone claims you provided inaccurate information that led to their financial loss. Whether you're an architect in Medford whose design oversight caused construction delays, or a marketing consultant in Holbrook whose campaign advice didn't deliver promised results, these situations fall under E&O coverage.
However, it's equally important to know what E&O doesn't cover. Intentional wrongdoing, criminal acts, and bodily injury or property damage claims fall outside E&O territory. Physical injuries and property damage are handled by General Liability insurance, which is why many Long Island businesses bundle both policies together for comprehensive protection. You can learn more about this complementary coverage at General Liability Insurance NY.
Do I Need E&O Insurance if I Work from Home in Holtsville?
This is a question we hear often from home-based professionals, and the answer is an emphatic yes. Your physical location has absolutely no bearing on your professional risk. The cost of e&o insurance is an investment in protection that every service provider needs, regardless of where they hang their shingle.
Consider this real-world scenario: You're a freelance IT consultant working from your home office in Holtsville, NY. A client claims your security recommendations were inadequate, and they suffered a data breach that cost them $50,000. They file a lawsuit against you. The court doesn't care that you work from your dining room table rather than a fancy office building in Patchogue—they only care whether you provided negligent advice.
Without E&O insurance, that lawsuit threatens your personal assets: your home, your savings, your family's financial security. A lawsuit can be filed against your business whether it operates from a commercial space in Medford or a spare bedroom anywhere on Long Island. The risk is identical, and the financial consequences can be devastating.
If you provide any kind of professional service or advice to clients for a fee—consulting, design work, financial planning, real estate services, bookkeeping, or countless other professional activities—you have exposure to claims. Your home office doesn't create a legal shield, which is precisely why E&O insurance exists. It protects both your professional reputation and your personal finances, giving you peace of mind to focus on serving your clients well.
Your Guide to Securing the Right E&O Coverage on Long Island
Understanding the true cost of e&o insurance is just the beginning. Throughout this guide, we've walked through the factors that shape your premiums—from the nature of your profession and the size of your business to your claims history and the specific realities of operating in New York. We've also shared practical strategies for managing these costs, whether through proactive risk management or smart policy structuring that balances protection with affordability.
But here's the thing: finding E&O coverage isn't about hunting for the absolute lowest price. It's about securing protection that actually fits your business. A policy that works for a consultant in Holbrook might not be right for an architect in Medford or a real estate agent in Holtsville. Your business is unique, with its own services, clients, and risks, and your insurance should reflect that.
This is where working with the right insurance partner makes all the difference. At Bay Harbour Insurance Agency, we take a genuinely client-centered approach. As a local Business Insurance Agency Patchogue NY, we've spent years helping professionals across Medford, Holbrook, Holtsville, and throughout Long Island find coverage that truly protects them. We understand the specific challenges you face—whether it's navigating New York's regulatory environment or managing the unique risks that come with serving clients on Long Island.
Because we're an independent agency, we're not locked into a single insurance carrier. Instead, we shop around on your behalf, comparing options from multiple providers to find the right coverage at the right price. We're not here to sell you the most expensive policy or the cheapest one. We're here to help you find the one that genuinely fits your needs and budget.
Your professional reputation and personal assets are too important to leave unprotected. Whether you're just starting out or you've been in business for decades, whether you work from a commercial office in Patchogue or a home office anywhere across Long Island, the right E&O coverage gives you the peace of mind to focus on what you do best.
Let's have a conversation about your specific situation. We'll answer your questions, explain your options, and help you find coverage that makes sense for your business. Contact Patchogue NY Insurance Agency today, and let's get started on protecting your professional future.