Compare Car Insurance for a New Car Before You Drive Home
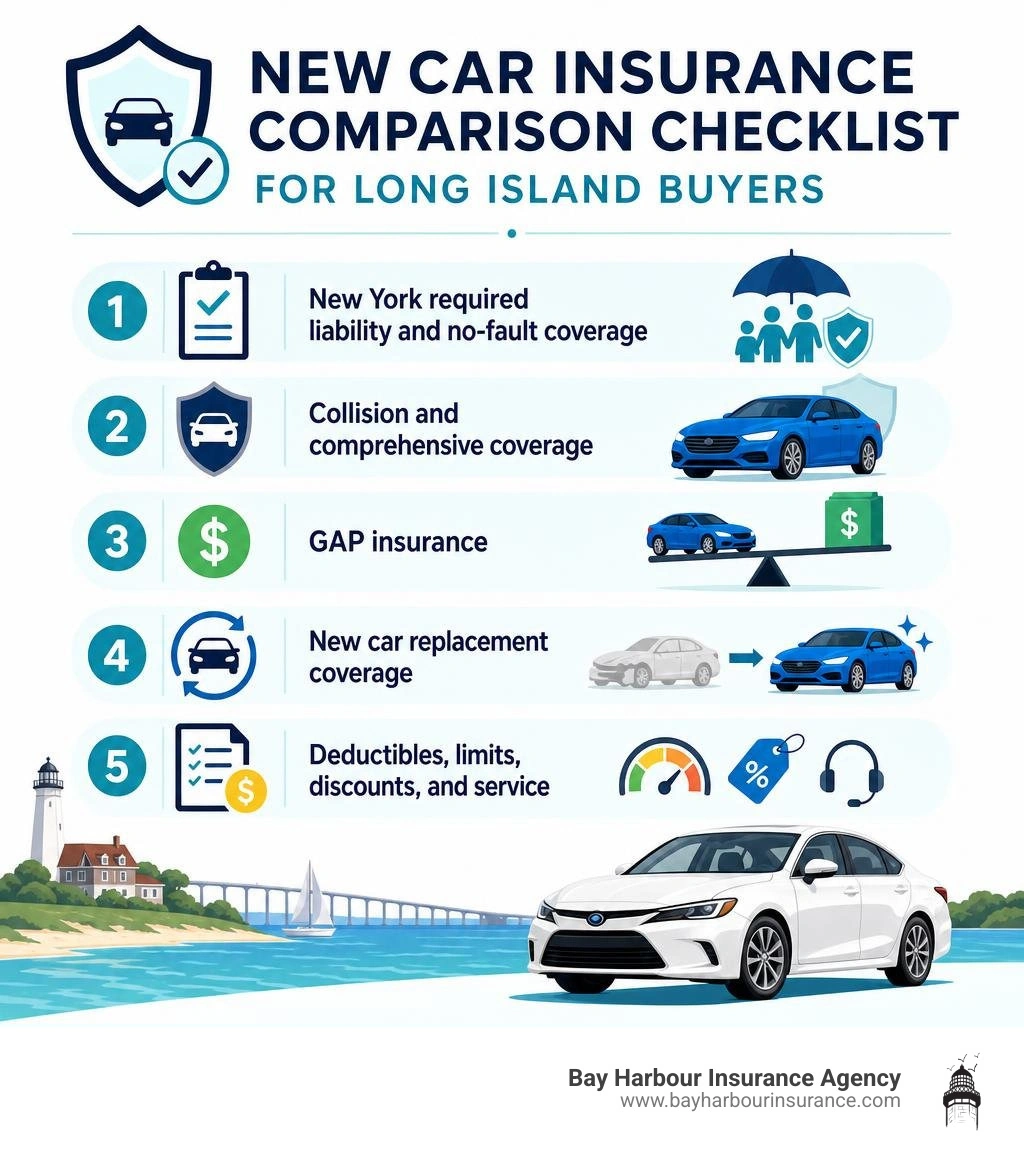
Car insurance for new car purchases should be active before you leave the dealership. For drivers in Patchogue, Holbrook, Holtsville, Medford, and across Long Island, the quick comparison is simple:
New vehicles can cost more to insure than older versions of the same model because they are worth more and may cost more to repair. Safety technology can help reduce risk, but it can also make repairs more complex. That is why it pays to compare the whole policy, not just the premium.
If you already have auto insurance, your policy may provide a short grace period to add the vehicle. But the deadline and temporary coverage level vary by insurer, and a dealership or lender may still require proof of specific coverage before release.
I am Rick Braile, and the next sections will help you compare coverage choices and avoid a gap when bringing home your new car.
Similar topics to car insurance for new car:
Timeline, Grace Periods, and Updating Existing Policies
Taking delivery of a new vehicle is an exciting milestone, but navigating drive-off requirements demands careful timing. When you buy a new car, insurance cannot be treated as an afterthought. Dealerships and financial institutions across Long Island will not permit you to drive off the lot without verified, active coverage that meets strict state regulations.
Whether you are picking up a commuter sedan in Patchogue or purchasing a family SUV in Medford, understanding your timeline guarantees a stress-free key handoff. You can learn more about state guidelines through our guide on auto insurance new york state.
When to Bind Car Insurance for New Car Deliveries
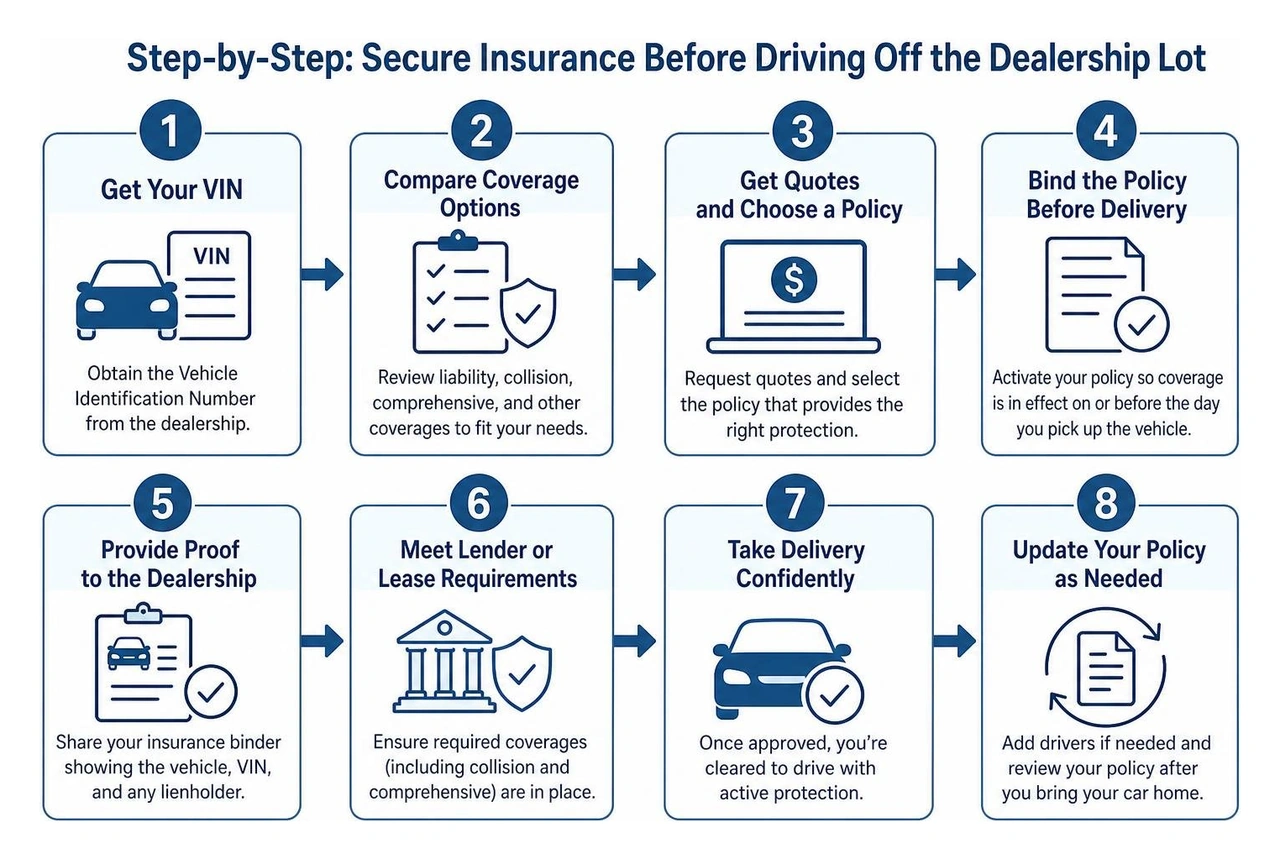
You must secure active coverage on or before the day you pick up your vehicle. Ideally, drivers in New York should start requesting quotes and selecting coverage options as soon as they commit to a specific vehicle and receive its Vehicle Identification Number (VIN).
Dealerships require a physical or digital copy of an active insurance binder naming the vehicle, its VIN, and any relevant lienholder details before releasing the keys. If you are securing financing or starting a lease, your financial institution will mandate specific minimum physical damage coverages (collision and comprehensive) before finalizing the contract. Binding your policy prior to delivery day ensures your vehicle is fully protected the second its tires hit the street.
Understanding Insurance Grace Periods for Existing Policyholders
If you currently maintain auto insurance on another vehicle, your carrier may offer a policy grace period. Across the industry, grace period windows generally range from 7 to 30 days. This provision automatically grants temporary protection for your newly acquired vehicle, giving you a small cushion of time to contact your provider and formally add the car to your policy.
However, relying entirely on a grace period carries notable risks:
- Coverage Limitations: A grace period typically carries over the exact coverage levels of the vehicle listed on your existing policy. If your older vehicle only carries state-minimum liability, your brand-new car will lack collision and comprehensive protection on the drive home.
- Actual Cash Value Restrictions: Standard policies pay out based on actual cash value. If a collision occurs during the grace period, standard payouts may fall short of total replacement value or leave you responsible for loan balances.
- Lender Verification: Even if your policy includes a 30-day grace period, most dealerships and leasing companies in Holbrook and Holtsville will not let you leave the lot without explicit proof of active coverage for that specific VIN.
If you need temporary short-term coverage solutions, review our resources on one week car insurance long island to understand your options.
Essential Coverage Types: Full Coverage, GAP, and New Car Replacement
Insuring a brand-new vehicle requires looking beyond basic legal mandates. While state law establishes minimum liability guidelines, protecting a modern, high-value asset involves building a comprehensive safety net.
Determining the Right Car Insurance for New Car Protection
Drivers throughout New York must navigate unique statutory mandates alongside practical vehicle protection needs. In Patchogue and Medford, local roadways bring a mixture of congested suburban traffic and high-speed highway merging, making adequate protection essential.
To properly protect your asset, build your policy starting with these core pillars:
- Personal Injury Protection (PIP): Mandatory under New York no-fault law, PIP covers medical expenses, lost work earnings, and essential daily expenses for drivers and passengers injured in an accident, regardless of who caused it. PIP includes specific caps on daily reasonable expenses and income loss compensation.
- Bodily Injury Liability: Protects your financial assets if you are found legally responsible for causing physical injury to others. Standard minimum split limits of $25,000/$50,000 exist, but choosing higher policy limits provides crucial financial protection against severe claims.
- Property Damage Liability: Pays for damage your vehicle causes to another person's property, such as another vehicle, guardrail, or structure.
- Statutory Uninsured/Underinsured Motorist Coverage: Protects you and your passengers if you are struck by a driver who carries no insurance or insufficient liability limits. For broader geographical protection outside the state, adding supplementary uninsured/underinsured motorist (SUM) coverage is recommended.
- Comprehensive & Collision: Often referred to alongside liability as full coverage car insurance, collision pays for vehicle damage resulting from an impact with another vehicle or object. Comprehensive handles non-collision losses, including theft, vandalism, weather damage, or hitting an animal.
For deeper insights on how coverage details work in practice, read ValuePenguin's guide on new car insurance.
GAP Insurance vs. New Car Replacement Endorsements
The moment you drive a brand-new vehicle off the lot, its market value drops due to depreciation. If your vehicle is totaled in a major collision or stolen shortly after purchase, standard actual cash value claim payouts may be significantly lower than the total amount you owe on your loan or lease.
To bridge this financial vulnerability, consider two specialized endorsements:
- GAP (Guaranteed Asset Protection) Insurance: Pays the direct financial shortfall between the actual cash value payout from your primary auto policy and the remaining balance on your vehicle financing or lease contract. If you put down a modest deposit, GAP coverage prevents you from paying thousands of dollars out of pocket for a car you no longer drive.
- New Car Replacement Coverage: Instead of settling for actual cash value minus depreciation, this coverage endorsement pays to replace your totaled vehicle with a brand-new vehicle of the same or comparable make and model year. In New York, certain endorsements will cap payouts up to 120% of the original manufacturer suggested retail price (MSRP) for vehicles under three years old.
- Original Equipment Manufacturer (OEM) Parts Coverage: Ensures that post-accident repairs utilize factory-fresh manufacturer parts rather than generic aftermarket components, maintaining your new car’s structural integrity and resale value.
Drivers can explore detailed coverage mechanics in FinanceBuzz's analysis of new vehicle insurance.
Smart Strategies for Finding Car Insurance for New Car Purchases
Securing high-quality insurance does not mean paying inflated rates. Vehicle owners across Long Island can take advantage of practical strategies to maintain robust protection while managing household expenses effectively.
Factors That Influence Premium Rates on New Vehicles
Insuring a brand-new vehicle costs roughly 10% more on average than insuring a four-year-old model of the exact same make and model. This rate difference stems primarily from higher actual cash values and expensive onboard technology. Sophisticated collision avoidance sensors, camera systems, and electric powertrains significantly increase windshield and body panel repair costs.
However, premium variations between vehicle styles can be drastic:
Modern safety technology like automatic emergency braking, lane departure alerts, and adaptive headlights lower accident risks and can unlock valuable safety feature discounts with your insurance carrier.
To explore savings options for cost-conscious drivers, check out our guide to cheap car insurance long island. Drivers with limited annual mileage can also evaluate telematics through usage based insurance save money.
How Local Agents Source Car Insurance for New Car Buyers
As an independent agency protecting families and business owners across Holbrook, Holtsville, Patchogue, and Medford, we do not limit our clients to a single corporate policy menu. Independent agents review policy structures across multiple reputable carriers to match your personal risk profile and driving habits.
Working with a local agent provides distinct advantages:
- Customized Deductibles: Tailoring collision and comprehensive deductibles to align with your personal cash flow.
- Bundling Discounts: Combining your vehicle protection with home, condo, or renters policies to secure significant multi-policy savings.
- Local Claim Advocacy: Having an agent located on Long Island who understands regional driving risks, local repair facility networks, and state regulatory standards guarantees personal, direct support when filing a claim.
Learn how independent advice simplifies carrier evaluations with our car insurance quotes complete guide.
Frequently Asked Questions About New Vehicle Insurance
How much more does it cost to insure a new car compared to an older car?
On average, a brand-new vehicle costs about 10% more to insure than a four-year-old version of the same make and model. This cost difference exists because newer cars have a higher actual cash value and feature complex technology, such as radar sensors and cameras integrated into bumpers and windshields, which increase repair expenses after an accident.
Do I need GAP insurance if I make a large down payment?
If you make a substantial down payment—typically 20% or more of the vehicle's purchase price—you may not need GAP insurance. A large down payment creates immediate equity in the vehicle, keeping your outstanding loan balance below the car's market value. However, if you lease a vehicle or finance with a low down payment, GAP insurance remains a vital safeguard against rapid early-stage depreciation.
What information do I need to get insurance before leaving the dealership?
To secure an active policy binder before driving off the lot in Holbrook, Holtsville, or Medford, you will need:
- The Vehicle Identification Number (VIN), year, make, and model of the car.
- Vehicle purchase price and lease/financing details, including the lender's exact legal name and loss-payee address.
- Driver’s license details for all household drivers.
- Your primary garage address in New York.
For global insights on delivery timing and coverage options, read RAA's answers on new vehicle policies.
Conclusion
Securing car insurance for new car purchases requires careful planning, but taking the right steps ensures your investment is fully protected the moment you collect your keys. From confirming mandatory New York state liability and no-fault coverages to adding GAP protection or new car replacement endorsements, tailored coverage gives you true financial peace of mind.
At Bay Harbour Insurance Agency, we take pride in serving our neighbors throughout Long Island, including driver communities in Patchogue, Holbrook, Holtsville, and Medford. As an independent, client-centered agency, we deliver personalized guidance, comparing carrier options to build protection that fits your lifestyle.
Before you step into the dealership showroom, let our team build the perfect insurance plan for your new vehicle. Get an auto insurance quote from Bay Harbour Insurance Agency today and hit the road with complete confidence.