Introduction: Protecting Your Practice on Long Island
The professional liability definition is the legal responsibility you have to clients for errors or negligence in your services. This insurance, also known as Errors & Omissions (E&O), protects your business from claims of financial loss due to your work. It covers legal defense costs, settlements, and judgments but excludes things like bodily injury or criminal acts, which require different policies.
This coverage is vital for service-based professionals across Long Island, from accountants in Medford to IT consultants in Holtsville. Imagine you're a consultant in Patchogue, and a client claims your advice led to a $50,000 loss. Even if the claim is baseless, the legal fees alone could cripple your business without this protection.
This is a daily reality for professionals throughout New York, including architects in Holbrook and firms across Long Island. Unlike general liability, which covers physical damages, professional liability specifically addresses financial harm from your services. For business owners in Patchogue, Holbrook, Holtsville, and Medford, this coverage is often a requirement for client contracts or state licensing.
This guide will explain what professional liability insurance covers, who needs it, and how much it costs, so you can protect your New York business and reputation.
Understanding the Core Professional Liability Definition and Coverage
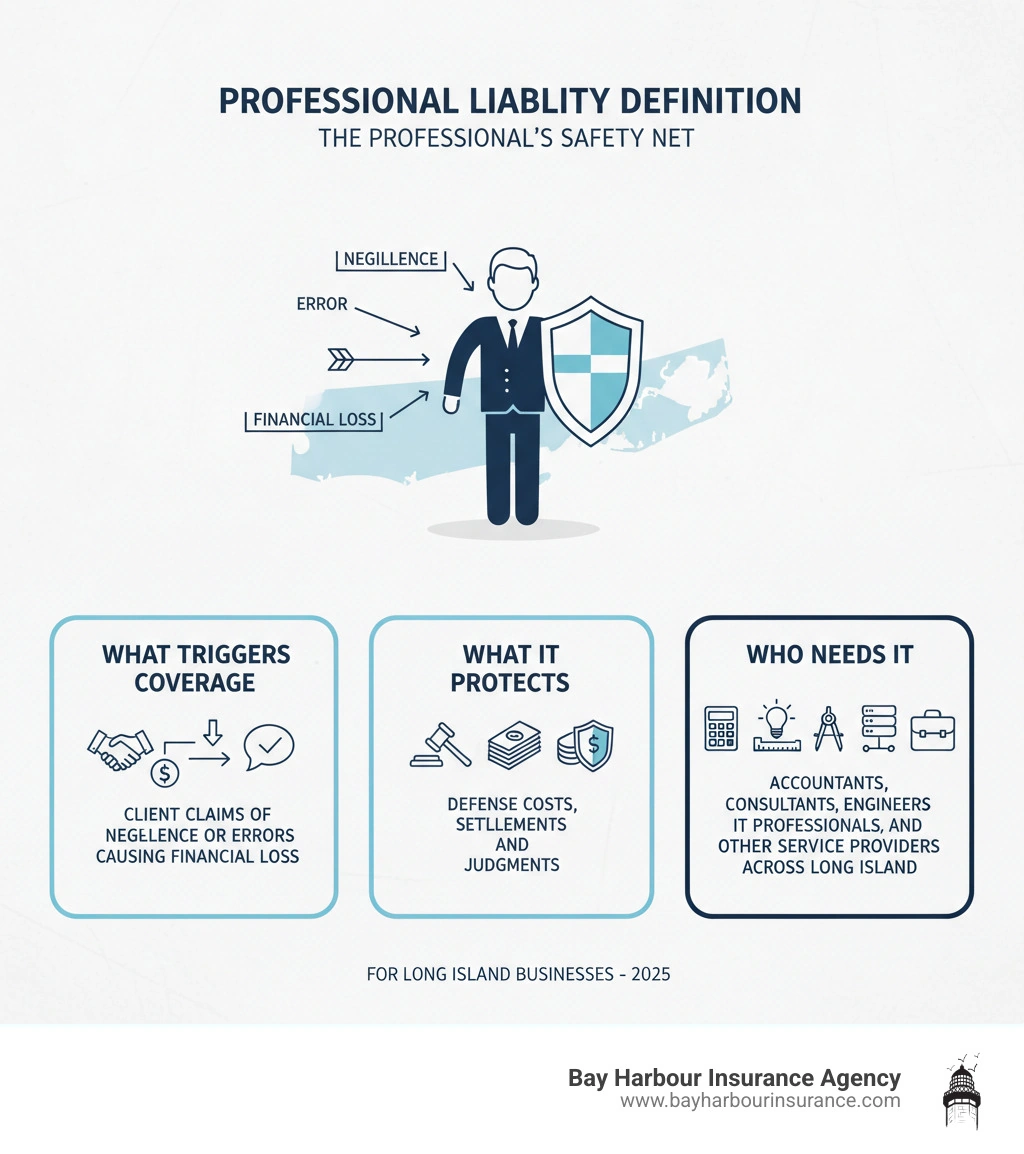
At its core, the professional liability definition refers to your legal responsibility for the services you provide. If a client in Holtsville or Medford suffers a financial loss due to your advice, oversight, or an honest mistake, they can hold you accountable. Professional liability insurance, or Errors & Omissions (E&O), is designed to protect you from claims of negligence, misrepresentation, or inaccurate advice.
This coverage is a financial shield, paying for your defense costs, settlements, and judgments. Even if a lawsuit is meritless, defending it can cost thousands. This insurance is critical for financial loss coverage, not physical harm. For example, if a marketing campaign underperforms or a software recommendation causes disruptions for a client on Long Island, this policy responds. You can learn more at Professional Liability Explained.
A Clear Professional Liability Definition for Your Business
For your New York business, this coverage protects you when clients claim your professional work—not a physical product—caused them to lose money. Depending on your industry, it might be called Errors & Omissions (E&O) for a consultant in Patchogue or malpractice insurance for a medical professional. For an architect in Holbrook, a design oversight causing delays is a professional liability issue. Carrying this insurance not only protects your finances but also improves your New York business reputation, as many clients on Long Island require it before signing a contract.
What It Covers vs. What It Doesn't
Knowing the boundaries of your policy is crucial for any professional in Holtsville or Medford.
What your policy typically protects you from:
Your policy covers claims of negligence, misrepresentation, and omissions that result in client financial loss. This includes an accountant's calculation error in Medford or an engineer's design oversight in Patchogue. Many policies also extend to copyright infringement or personal injury (libel/slander) related to your professional work. Most importantly, it covers defense costs, which can be devastating for a small business in Holbrook or anywhere on Long Island, even for baseless lawsuits.
What falls outside this protection:
Professional liability does not cover bodily injury or property damage (that's for general liability). It also excludes criminal acts and intentional fraud. Employment disputes, like wrongful termination, require separate Employment Practices Liability coverage. While related, dedicated cyber liability insurance is typically needed for data breaches, a topic we cover here: More on the Risks Without Cyber Insurance. Finally, issues you knew about before buying the policy (known prior acts) are generally excluded. A complete protection strategy for your New York business often involves a combination of coverages.
Who Needs This Insurance in Patchogue, Holbrook, and Beyond?
If you provide professional services or expert advice on Long Island, you likely need professional liability insurance. It's a business necessity in today's litigious world.
For many professionals across New York, this coverage is a core business requirement. Clients in Patchogue and Holbrook often demand it before signing a contract. Having this insurance also gives you a competitive edge, demonstrating professionalism and a commitment to protecting client interests. For businesses from Medford to Holtsville, this can make all the difference. State regulations also play a role, with certain professions required to carry it to maintain their license. Even when not mandated, the peace of mind is invaluable. We explore more protection strategies in our article: More on Business Owner Protection.
[LIST] of Common Professions That Benefit
Some professions face higher risks simply because of what they do. Accountants handle financial data where a miscalculation can be costly. IT consultants implement systems where failure can shut down a business. Architects and engineers create designs where errors lead to expensive delays. Marketing agencies face claims of copyright infringement. Real estate agents in Medford handle transactions where misrepresentations can cost thousands. Lawyers in Holtsville need malpractice coverage for incorrect legal advice. Healthcare professionals on Long Island require it to protect against claims of medical negligence. The common thread is that their expertise directly impacts clients' financial well-being. For related leadership protection, consider exploring: Learn about Directors & Officers Insurance Basics.
Is It Required for My Long Island Business?
The short answer is: it depends, but it's increasingly necessary. Client contracts often specify minimum coverage amounts as a condition of doing business in New York. Professional licensing boards in certain fields mandate this insurance to protect consumers. New York state mandates vary by profession, but even when optional, the practical reality for businesses in Holbrook and Patchogue makes it essential. Beyond formal requirements, knowing you're protected allows you to operate without the constant fear of a single error bankrupting you. The question isn't whether you can afford professional liability insurance—it's whether you can afford to be without it. You can learn more here: Professional liability insurance | Britannica.
Decoding Your Policy: Key Features and Common Claims
Understanding your professional liability policy is key to ensuring your business in Patchogue or Medford is protected. The professional liability definition is built around protecting you from claims of financial harm, but the details of your policy determine how that protection works.
Most claims stem from clients believing you made an error that cost them money. An accountant's miscalculation in Medford, a consultant's flawed advice in Holtsville, or an architect's oversight in Holbrook can all lead to lawsuits. Let's walk through the critical aspects of your policy.
How Claims-Made Coverage and Retroactive Dates Work
Most professional liability policies are "claims-made," meaning timing is everything. For coverage to apply, the claim must be made against you and reported to your insurer while your policy is active. The error itself must also have occurred on or after your policy's retroactive date.
This retroactive date is your coverage start point for past work. When you first buy a policy, it usually matches the start date. If you switch insurers, you must negotiate to maintain your original retroactive date to avoid creating a gap in coverage for past work. This is why maintaining continuous coverage is vital for any business on Long Island. A lapse can leave years of your work uninsured if a claim arises later, a major risk for professionals in Medford and Holtsville.
Understanding Tail Coverage (Extended Reporting Period)
What happens if you retire, sell your Long Island business, or change careers? If you cancel your claims-made policy, you lose coverage for future claims related to your past work. Tail coverage, or an Extended Reporting Period (ERP), solves this. It's a one-time purchase that extends your window to report claims after your policy has ended.
This is essential protection for any professional in Patchogue or Holbrook who is closing a chapter. Clients can file claims years later. Tail coverage ensures your past work won't become a future financial disaster. It's a crucial investment for protecting your assets in retirement or your next venture in New York.
Common Exclusions from the Standard Professional Liability Definition
Understanding what your policy doesn't cover is just as important. The standard professional liability definition has clear boundaries.
- Intentional Wrongdoing and Fraud: Policies cover honest mistakes, not deliberate deception or criminal acts.
- Bodily Injury and Property Damage: These are covered by general liability insurance, not professional liability.
- Employment Disputes: Claims like wrongful termination require separate Employment Practices Liability Insurance (EPLI).
- Known Prior Acts: You cannot buy coverage for a problem you were already aware of before the policy started.
- Contractual Liability: Pure breach of contract claims (without a professional error) are often excluded.
- Fines and Penalties: Government-imposed fines are generally not covered.
Knowing these exclusions helps you build a complete insurance strategy for your business, whether it's in Medford, Holtsville, or anywhere on Long Island.
The Cost of Protection: What Influences Premiums on Long Island?
Professionals across Long Island, from Patchogue to Medford, often ask about cost. While every policy is unique, the median cost for professional liability insurance is around $61 per month ($735 annually). Most New York businesses pay between $600 and $1,200 per year.
Your premium is a personalized price based on your specific risks. An IT consultant in Holbrook faces different exposures than a marketing agency in Holtsville, and your premium reflects that.
Understanding these cost drivers helps you make smart decisions for your business in Patchogue or Holbrook.
Key Factors Affecting Your Premium
- Profession and Industry Risk: High-stakes fields like healthcare and legal services have higher premiums.
- Business Size: More employees and higher revenue generally mean a higher premium.
- Location: The litigation environment in New York and on Long Island can influence rates.
- Claims History: A clean record can lower your costs, while past claims can increase them.
- Coverage Limits: Higher limits provide more protection but cost more.
- Experience and Risk Management: Experienced professionals with strong risk management practices may qualify for lower rates.
Average Costs by Profession
The professional liability definition translates into different risk levels and costs by industry. While you need a personalized quote, these averages provide a general idea:
- Architects and engineers average around $239 per month due to the high financial stakes of construction projects.
- Technology companies and IT consultants average about $146 monthly, as their services are critical to business operations.
- Healthcare professionals on Long Island average around $38 per month, though this varies widely by specialty.
- Miscellaneous professionals (consultants, marketers) average about $62 monthly.
These figures show why a custom quote is essential for your business, whether it's in Medford, Holtsville, or anywhere in New York.
Frequently Asked Questions for New York Professionals
We've answered the most common questions we hear from professionals in Patchogue, Holbrook, and across Long Island to help you understand this essential coverage.
What's the difference between professional liability and general liability?
This is the most common question for business owners in New York. Simply put: professional liability covers financial loss from your work, while general liability covers physical accidents. Professional liability is for claims of errors or negligence in your services (e.g., bad advice from a consultant in Holtsville). General liability is for bodily injury or property damage (e.g., a client slipping in your Medford office).
Most businesses on Long Island need both. Here's a quick comparison:
To learn more, read our guide: Learn about General Liability Insurance in NY.
What are the consequences of not having professional liability insurance?
Operating without this insurance is a gamble that could cost you everything. The consequences for your business in Patchogue or Holbrook can be devastating:
- Out-of-Pocket Legal Fees: Defending a lawsuit is expensive, even if you win. These costs come directly from your pocket.
- Catastrophic Settlements: A successful claim could lead to a judgment that bankrupts your business.
- Reputational Damage: A lawsuit is public record and can scare away potential clients across Long Island.
- Loss of Business Opportunities: Many contracts, especially with larger clients in New York, require proof of insurance.
- Personal Asset Risk: For sole proprietors, your personal assets (home, savings) could be at risk.
The modest cost of coverage is minor compared to the potential consequences of going without it in places like Holtsville or Medford.
Will it cover me even if a lawsuit is baseless?
Yes, and this is one of its most valuable features. Your professional liability definition includes coverage for defense costs, regardless of a claim's merit. Your insurer will pay for attorneys and court costs to defend you against a frivolous lawsuit from a client in Patchogue.
This protection provides enormous peace of mind for professionals across New York, from Holbrook to Medford to Holtsville. You can focus on your business knowing you have an ally ready to cover the costs of a legal defense, allowing you to continue serving your clients on Long Island.
Secure Your Professional Future on Long Island
For professionals across New York, understanding the professional liability definition and securing coverage is essential. Whether you're in Holbrook, Holtsville, or Medford, this insurance is your financial safety net against claims that your services caused a client harm.
We've covered what this insurance does, who needs it on Long Island, and how policies like claims-made coverage work. The key benefits are clear: it protects you from devastating lawsuits, covers legal defense costs even for baseless claims, and helps you win contracts. It shows clients in Patchogue and across New York that you are a responsible professional.
At Bay Harbour Insurance Agency, we know a one-size-fits-all approach doesn't work. A consultant in Holtsville has different risks than an architect in Holbrook. We take a client-centered approach, learning about your unique business before recommending coverage.
As an independent agency, we work for you, not an insurance carrier. We shop the market to find the right protection for your needs and budget. We are your advocates, ensuring you understand your policy and have the right protection for your business in Medford or anywhere on Long Island.
Don't wait for a claim to happen. Contact us to protect what you've built and secure your professional future.
Contact us to discuss your business insurance needs in Patchogue, NY