
Why an ALTA Homeowner's Policy Matters for Long Island Buyers
An ALTA Homeowner's Policy is enhanced owner's title insurance for eligible one-to-four family homes. It protects against title problems that may not appear in a standard owner's policy, including certain unrecorded defects, permit and zoning issues, and some events that happen after closing, such as a forged deed or a neighbor's new encroachment.
For homebuyers in Patchogue, Holbrook, Holtsville, Medford, and across Long Island, it can help protect the legal right to own, use, and later sell a home. Unlike property insurance, which addresses future physical damage like fire or storms, title insurance addresses ownership problems tied to the property's past.
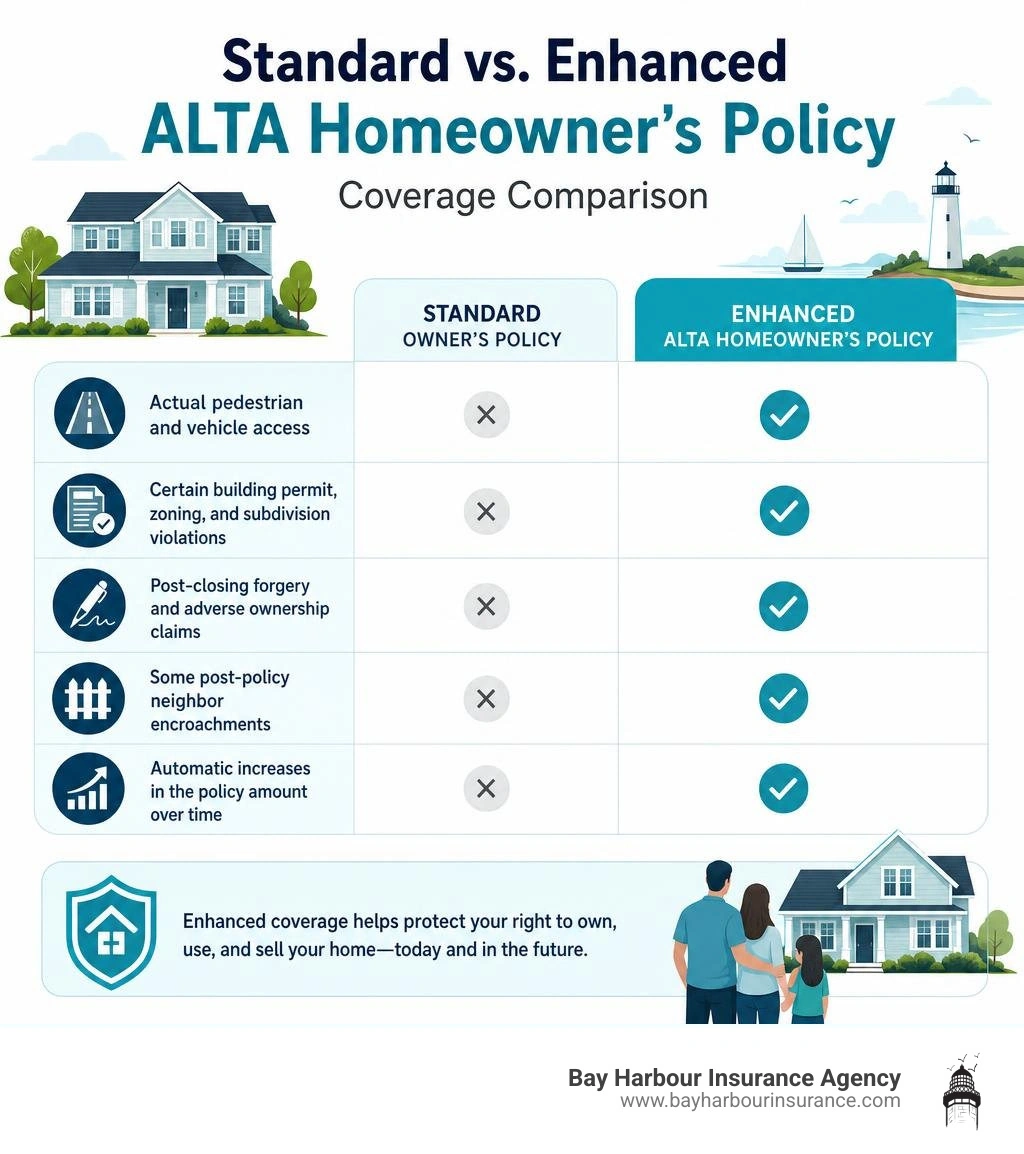
A standard owner's policy generally focuses on defects that existed on or before the policy date. The enhanced policy can add protections such as:
- Actual pedestrian and vehicle access
- Certain building permit, zoning, and subdivision violations
- Post-closing forgery and adverse ownership claims
- Some post-policy neighbor encroachments
- Automatic increases in the policy amount over time
Eligibility and exact coverage depend on the policy form, property, state availability, listed exceptions, and any coverage limits or deductibles. Reviewing the title commitment before closing is essential.
I'm Rick Braile, and the rest of this guide explains how enhanced title coverage fits alongside the broader home insurance protection Long Island owners need.
Terms related to alta homeowner's policy:
Understanding the ALTA Homeowner's Policy and Standard Title Coverage
When closing on a home in New York, understanding your paperwork is essential. A standard title policy protects your lender or covers baseline risks shown in public records up to closing. In contrast, an enhanced alta homeowner's policy broadens that security net to protect personal home equity against unrecorded title defects and unexpected ownership challenges.
The title company performs thorough upfront research to clear clouds on title before ownership transfers. Still, hidden title defects slip through. According to national industry research, fraud and forgery claims represent 21% of total claim dollars spent by title insurers on claim expenses and losses, with an average claim cost topping $143,000.
A standard policy acts as a legal contract of indemnity covering errors on public record, but the enhanced residential form includes an active duty to defend your property rights in court. Legal analyses like Explaining the ALTA homeowner's policy of title insurance highlight how the expanded policy jacket transforms title protection from a passive historical record search into an active safeguard.
Core Protections of an ALTA Homeowner's Policy
A core distinction of the expanded policy is how it addresses practical, everyday land ownership. Under a standard title form, having "legal access" might simply mean your land touches a dedicated public right-of-way on a map, even if a steep ravine prevents you from actually driving onto the parcel. The enhanced policy requires actual physical pedestrian and vehicular access based on the legal street address.
The 2021 ALTA revisions also account for modern real estate transactions, covering title defects arising from improper remote online notarization (RON) or repudiated electronic signatures. Furthermore, the policy insures against forced remediation if an existing structure violates recorded restrictive covenants, while explicitly stripping out and repudiating historical discriminatory covenants so they never cloud your property rights. Reviewing the standard conditions in the ALTA Owner's Policy shows just how substantial these enhanced revisions are.
Post-Closing Protections in an ALTA Homeowner's Policy
Standard title insurance freezes its protection at the exact moment your deed is stamped at the county recording office. If a rogue actor forges a deed conveying your property two years later, a standard policy offers no relief.
Under an enhanced homeowner policy, post-policy occurrences are explicitly covered:
- Post-Closing Forgery and Impersonation: Protects against criminals filing fraudulent transfer deeds or unauthorized mortgages against your home equity.
- Adverse Possession Claims: Defends you if an adjoining party attempts to claim legal title to your parcel through post-policy adverse possession or prescriptive easements.
- Post-Policy Neighbor Encroachments: Covers situations where an adjoining neighbor builds a structure (other than boundary walls or fences) that crosses your lot line after your purchase date.
- Supplemental Real Estate Taxes: Shields you from retroactive supplemental taxes assessed for home construction or improvements completed prior to your closing date.
- Subsurface Extraction Damage: Covers damage to your existing residence caused by third parties exercising mineral, oil, gas, or geothermal extraction rights.
Eligibility, Deductibles, and Policy Sub-Limits
The enhanced homeowner policy is not available for every transaction. To qualify, the property must be an improved, existing one-to-four family residential parcel. Commercial warehouses, vacant subdivisions, and properties purchased under corporate entities or standard LLCs are excluded. The policyholder must be a "Natural Person" (a human being) or a qualifying estate planning entity, such as a revocable living trust established for asset distribution.
Unlike standard title policies that operate without deductibles, the expanded protections for municipal violations carry specific deductibles and liability caps. Understanding these sub-limits is vital when exploring Homeowners Insurance Basics.
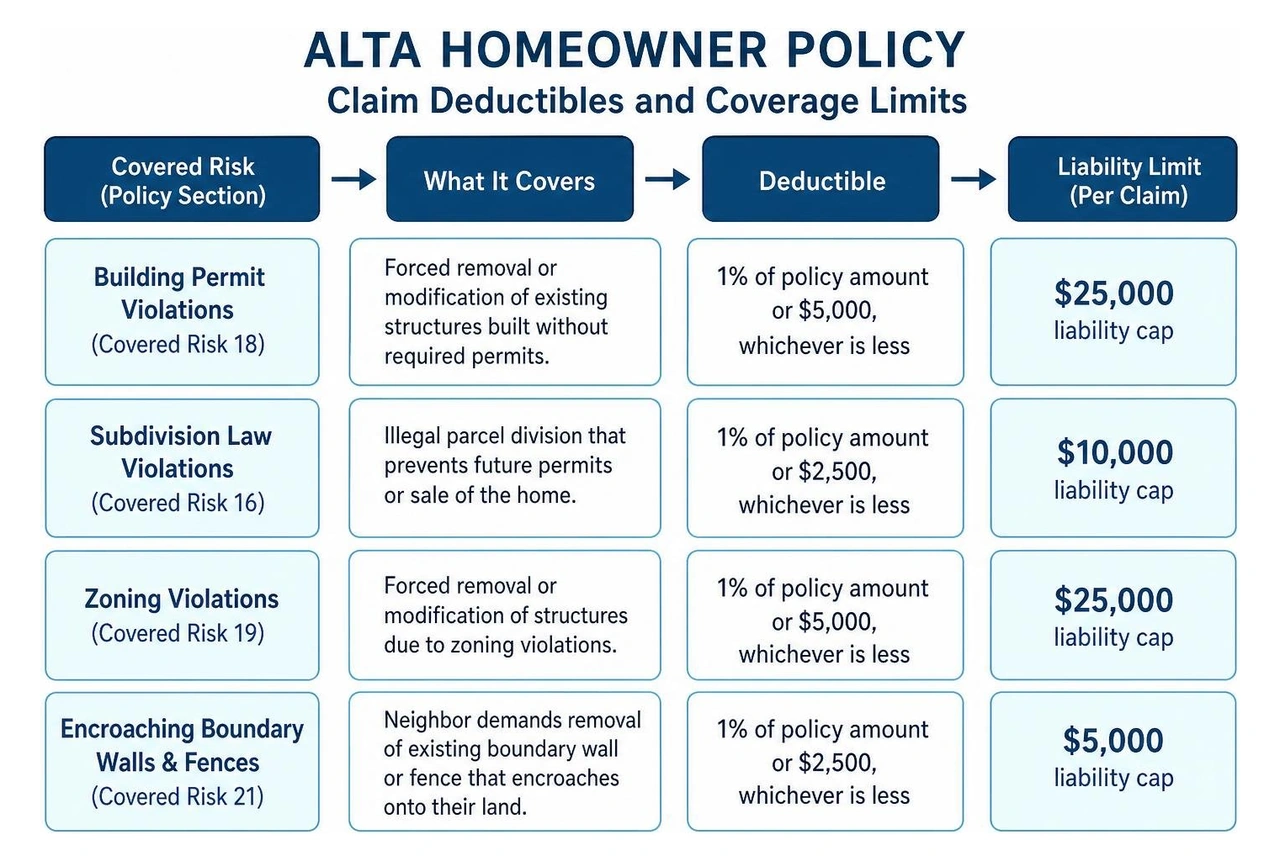
- Building Permit Violations (Covered Risk 18): If a local municipality forces you to remove or modify an existing structure built by a previous owner without required building permits, the policy pays up to a standard $25,000 liability cap after a deductible (typically 1% of the policy amount or $5,000, whichever is less).
- Subdivision Law Violations (Covered Risk 16): If a previous owner illegally divided the parcel, preventing you from obtaining future building permits or selling the home, coverage applies up to a $10,000 liability cap after a modest deductible (often 1% or $2,500).
- Zoning Violations (Covered Risk 19): If forced to remedy or remove structures because your home violates zoning ordinances, coverage helps offset modification expenses up to $25,000.
- Encroaching Boundary Walls and Fences (Covered Risk 21): If a neighbor demands removal of an existing boundary fence or wall that encroaches onto their land, coverage applies up to a designated sub-limit (often $5,000) after a deductible.
Inflation Protection and Living Expense Allowances
Real estate values fluctuate, but over time, residential property on Long Island historically appreciates. A standard title policy stays fixed at the original purchase amount indefinitely unless you purchase supplemental endorsements. The enhanced homeowner policy builds in an automatic appreciation adjustment: the amount of insurance increases by 10% each year for the first five years, reaching an automatic cap of 150% of the initial policy value at no additional cost.
Additionally, if a covered title defect prevents you from using or occupying the home, the enhanced policy covers:
- Substitute Residence Rent: Reimburses the reasonable actual cost of renting an equivalent home while the title defect is litigated or cured.
- Personal Property Relocation: Covers moving and storage expenses to transport household belongings within a 50-mile radius of the property.
- Unsuccessful Defense Increase: If the title insurer initiates legal action to defend or clear your title and loses in court, the total amount of insurance automatically increases by 15% to offset ongoing property valuation loss.
Having adequate title limits ensures your equity is shielded, just as keeping your Dwelling Insurance Coverage NY updated safeguards the physical structure.
How Title Insurance Complements P&C Coverage on Long Island
Title insurance and Property & Casualty (P&C) homeowners insurance operate on opposite timelines:
- Title Insurance: Retrospective. You pay a single, one-time premium at closing to protect against undiscovered legal defects originating in the past.
- Homeowners Property Insurance: Prospective. You pay recurring annual or monthly premiums to safeguard against future physical perils, such as fire, storms, burst pipes, and personal liability.
When preparing for homeownership and Buying Home Insurance First Time, pairing comprehensive title security with tailored property coverage is essential. In communities across New York, residential properties often carry decades of history.
Whether you are purchasing a ranch in Holbrook, a colonial in Medford, a historic property near the water in Patchogue, or an updated home in Holtsville, older renovations or shared boundary fences are common. A title policy ensures no prior owner's contractor lien or unpermitted garage addition disrupts your ownership, while our property coverage steps in if winter winds damage your roof or a pipe bursts in the basement.
In Holbrook, Holtsville, Medford, and Patchogue, having both legal title protection and dedicated property insurance ensures your home is protected from every angle across Long Island and throughout New York.
Frequently Asked Questions About ALTA Title Insurance
Who qualifies to purchase an enhanced homeowner title policy?
To qualify, the property must be an improved one-to-four family residential dwelling, and the named insured must be an individual (natural person) or a designated estate planning trust. Commercial businesses, LLCs, and unimproved vacant land do not qualify for this specific form and must use standard or commercial title policies.
How does post-closing inflation coverage work under this policy?
The policy features an automatic annual 10% increase to the baseline coverage amount for the first five years following closing, maxing out at 150% of the original purchase amount. This benefit requires no ongoing fees or additional premium payments and helps keep pace with market appreciation across New York.
Are unpermitted home additions covered by title insurance?
Under Covered Risk 18 of the ALTA Homeowner's Policy, if a municipal building department orders you to remedy or remove an existing structure built by a prior owner without proper permits, the insurer covers loss up to the policy limit (typically $25,000) after you pay the policy deductible. Standard title policies exclude unpermitted structures entirely unless customized endorsements are attached.
Conclusion
Securing a home requires protecting both your legal title and the physical structure. While an enhanced title policy protects your past property rights, having the right property and casualty coverage safeguards your future.
At Bay Harbour Insurance Agency, we are client-centered, independent agents dedicated to providing personal service for families throughout Long Island. Whether you are buying a home in Patchogue, Holbrook, Holtsville, or Medford, our team helps you design the right property policies for your needs.
Explore our comprehensive options for Homeowners Insurance New York State to ensure your property remains protected for years to come.